Personal Finance Tips for 2026: 12 Habits That Build Real Wealth
Managing money well is less about earning a huge salary and more about building a few repeatable habits. These personal finance tips are designed for everyday people who want breathing room, not complicated spreadsheets or risky bets. If you can automate a handful of small decisions, you can change your entire financial trajectory over the next few years.
In 2026, with inflation cooling but prices still elevated, the fundamentals matter more than ever. Below you will find a practical, step-by-step framework covering budgeting, saving, debt, and investing, plus a few tools that make the process almost effortless.
Start With a Budget That Actually Sticks
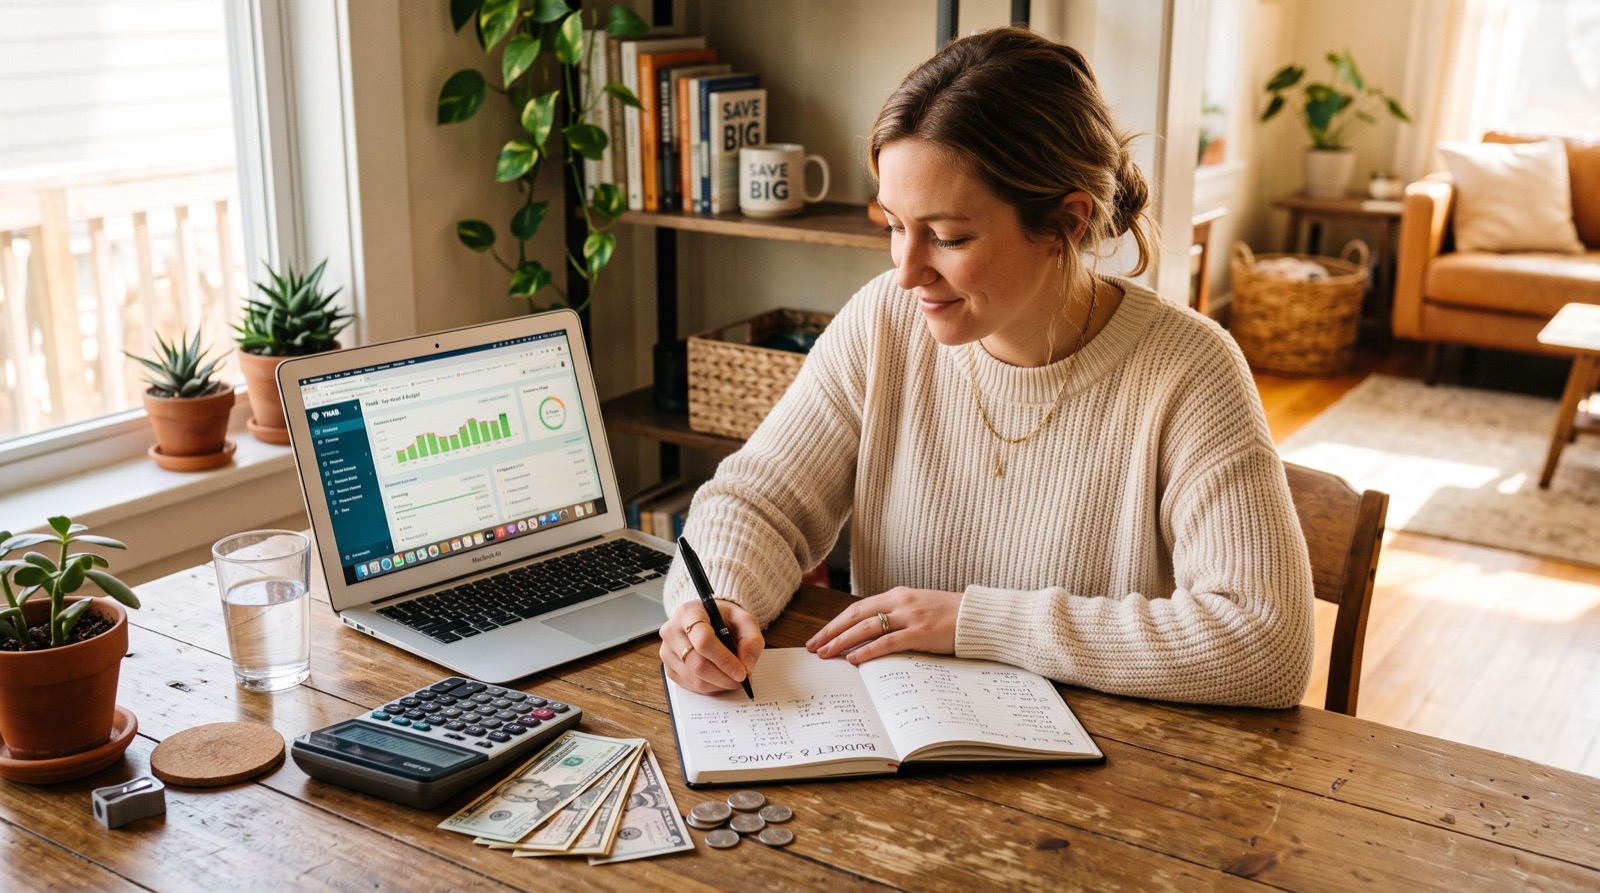
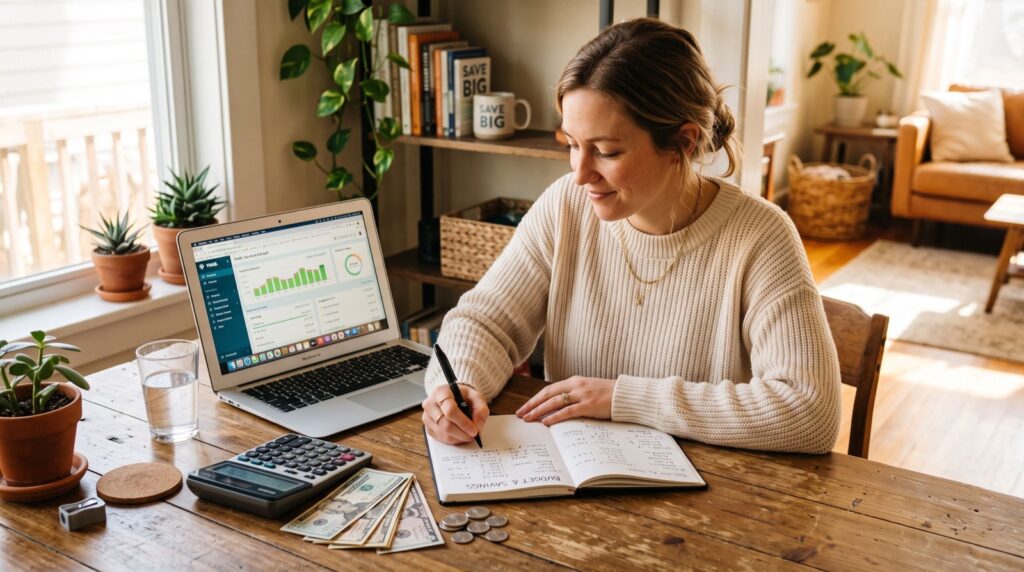
A budget is simply a plan for your money before the month begins. The problem with most budgets is that they are too strict, so people abandon them by week two. The fix is to keep it simple and forgiving.
The popular 50/30/20 method splits your after-tax income into needs, wants, and savings or debt payoff. It gives structure without forcing you to track every coffee. Adjust the ratios to fit your reality; the categories matter more than hitting exact percentages.
The 50/30/20 framework at a glance
| Category | Share of Income | What It Covers |
|---|---|---|
| Needs | 50% | Rent, groceries, utilities, insurance, minimum debt payments |
| Wants | 30% | Dining out, streaming, hobbies, travel |
| Savings & debt | 20% | Emergency fund, investing, extra debt payoff |
Build an Emergency Fund Before Anything Else
An emergency fund is the foundation every other money goal rests on. Without it, a single car repair or medical bill pushes you back into high-interest debt. Start with a modest target of one month of essential expenses, then build toward three to six months over time.
Keep this cash in a separate high-yield savings account so it is reachable but not tempting. Online banks in 2026 still offer rates far above traditional brick-and-mortar accounts, which means your safety net quietly grows while it waits.
How to fund it fast
- Automate a fixed transfer on every payday.
- Redirect one-time windfalls like tax refunds or bonuses.
- Sell unused items and deposit the proceeds directly.
- Bank the difference whenever a subscription is cancelled.
Why Do Small Automatic Habits Beat Willpower?
Willpower is a limited resource, and relying on it to save money almost always fails. Automation removes the daily decision entirely. When your savings transfer and bill payments happen on their own, good outcomes become the default rather than something you must choose again and again.
Research from behavioral economists shows that people save significantly more when enrollment is automatic. The U.S. Consumer Financial Protection Bureau offers free worksheets and guidance on building an emergency fund and everyday budget that pair perfectly with an automated system.
Attack High-Interest Debt Strategically
Debt is the single biggest drag on wealth building because interest compounds against you. Credit cards, in particular, can carry rates above 20%, which quietly erases any progress you make elsewhere.
Two proven payoff methods work well. The avalanche method targets the highest interest rate first to save the most money, while the snowball method clears the smallest balance first for quick motivation. Pick whichever keeps you consistent, because the best strategy is the one you actually follow.
A sample payoff plan
- List every debt with its balance and interest rate.
- Make all minimum payments to protect your credit.
- Throw every extra dollar at one target debt.
- Roll each cleared payment into the next debt.
Use the Right Tools to Track and Grow
The right apps turn good intentions into automatic behavior. A solid money app shows your spending by category, alerts you to unusual charges, and nudges you to save. If you send money to friends or receive a paycheck, a reliable Cash App guide can help you set up direct deposit and automated savings in minutes.
When your finances get more complex, consider working with trusted professionals who can tailor a plan to your situation. A one-time session with a fee-only advisor often pays for itself. For ongoing learning, bookmark clear, practical personal finance tips you can revisit as your income grows.
Invest Early and Let Compounding Work
Saving protects you; investing grows you. The earlier you start, the more time compounding has to multiply your contributions. Even small, regular investments in a diversified, low-cost index fund can outperform larger sums invested later.
If your employer offers a retirement match, contribute at least enough to capture it in full, because that match is an immediate, guaranteed return. After that, automate steady contributions and ignore the daily market noise. Time in the market consistently beats timing the market.
Beginner-friendly investing steps
- Capture any employer retirement match first.
- Open a tax-advantaged account such as an IRA.
- Choose a broad, low-fee index fund.
- Automate monthly contributions and leave them alone.
Protect Your Progress With Insurance and Credit
Building wealth is only half the job; protecting it is the other half. A single uninsured disaster can wipe out years of careful saving, so the right coverage is a core part of any sound money plan. Review your policies once a year rather than setting them and forgetting them.
Your credit score deserves the same attention. A strong score lowers the interest you pay on everything from cars to mortgages, which can save tens of thousands of dollars over a lifetime. Check your free credit report regularly, pay every bill on time, and keep your credit utilization low.
Simple ways to strengthen your credit
- Pay at least the minimum on every account by the due date.
- Keep card balances below 30% of your limit.
- Avoid opening several new accounts at once.
- Dispute any errors you find on your credit report.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Start by building a simple budget, saving a starter emergency fund, and paying off high-interest debt. Once those are in place, automate your savings and begin investing for the long term. These four steps cover the vast majority of what beginners need.
How much should I save each month?
Aim for at least 20% of your take-home pay split between savings, investing, and extra debt payoff. If that feels impossible, start with 5% and raise it one percentage point every few months until you reach a comfortable target.
Should I pay off debt or invest first?
Always secure a small emergency fund and any employer retirement match first. After that, prioritize paying off debt with interest rates above roughly 7%, then shift extra money toward investing for growth.
How do I stop living paycheck to paycheck?
Track your spending for one month to find leaks, automate a small savings transfer on payday, and cut one or two recurring costs. Small, consistent changes add up faster than a single dramatic overhaul.
Final Thoughts
Lasting financial security does not require a windfall; it requires consistency. Apply these personal finance tips one at a time, automate everything you can, and let your habits compound alongside your money. Begin with a single change this week, and your future self will thank you throughout 2026 and well beyond.